Uncategorized
Top 5 Lenders for Bad Credit Loans in Virginia: 2026 Rankings
Top 5 Lenders for Bad Credit Loans in Virginia: 2026 Rankings
Last updated: 2026-10-17
Trying to manage money in the Commonwealth can feel like driving through a thick fog when your credit score isn’t where it needs to be. Many Virginians find themselves staring at a sudden car repair bill or a medical invoice, searching for a lifeline that won’t sink their financial future. Whether you are dealing with a transmission failure on I-95 or a dental bill in Alexandria, the pressure to find quick cash can cloud your judgment.
Finding a lender requires looking past the flashy ads to see what actually matters. You need speed, transparency, and accessibility. It is not just about the amount of money you get today, but how much that money will ultimately cost you over the next six months. This list highlights options for people who need cash quickly but want to understand the fine print before signing anything.
- OppLoans
- MaxCash
- JetzLoan
- Vacu
- 1st Advantage
Evaluating Lenders Across the Old Dominion
We selected these lenders based on how accessible they are to residents in cities like Richmond, Norfolk, and Virginia Beach. The application process shouldn’t feel like a mountain of paperwork. Speed of funding is a massive factor for anyone in a crisis. An eviction notice or a utility shut-off notice doesn’t wait five or seven business days like a traditional bank might require for a manual review.
Getting your money quickly is vital. Some lenders provide funds within the same business day, while others take longer to process the paperwork. We also considered the impact of the inquiry on a FICO score. Many people cannot afford a dip in their rating during a tight spot. A “hard pull” can linger on your credit report for years, potentially affecting an auto loan or a mortgage later.
A “soft pull” is a much safer way to shop around without penalty. It lets you check your options without the fear of a sudden drop in your rating. If you are testing the waters, look for lenders that offer this flexibility so you can compare rates without any risk to your credit history.
Quick Comparison of Virginia Lending Options
| Lender | Loan Amounts | Funding Speed | Credit Check Impact | Key Feature |
|---|---|---|---|---|
| OppLoans | $500 – $5,000 | Same-day available | No impact on FICO | No hidden fees |
| MaxCash | $250 – $10,000+ | Minutes to approve | Free inquiry | Multiple loan types |
| JetzLoan | $500 – $35,000 | As little as 24 hours | No hard credit pull | High customer rating |
| Vacu | As low as $100 | See site | See site | Refinance options |
| 1st Advantage | Up to $750 | See site | No credit check option | Short-term focus |
Ranking the Best Options for Bad Credit in Virginia
1. OppLoans
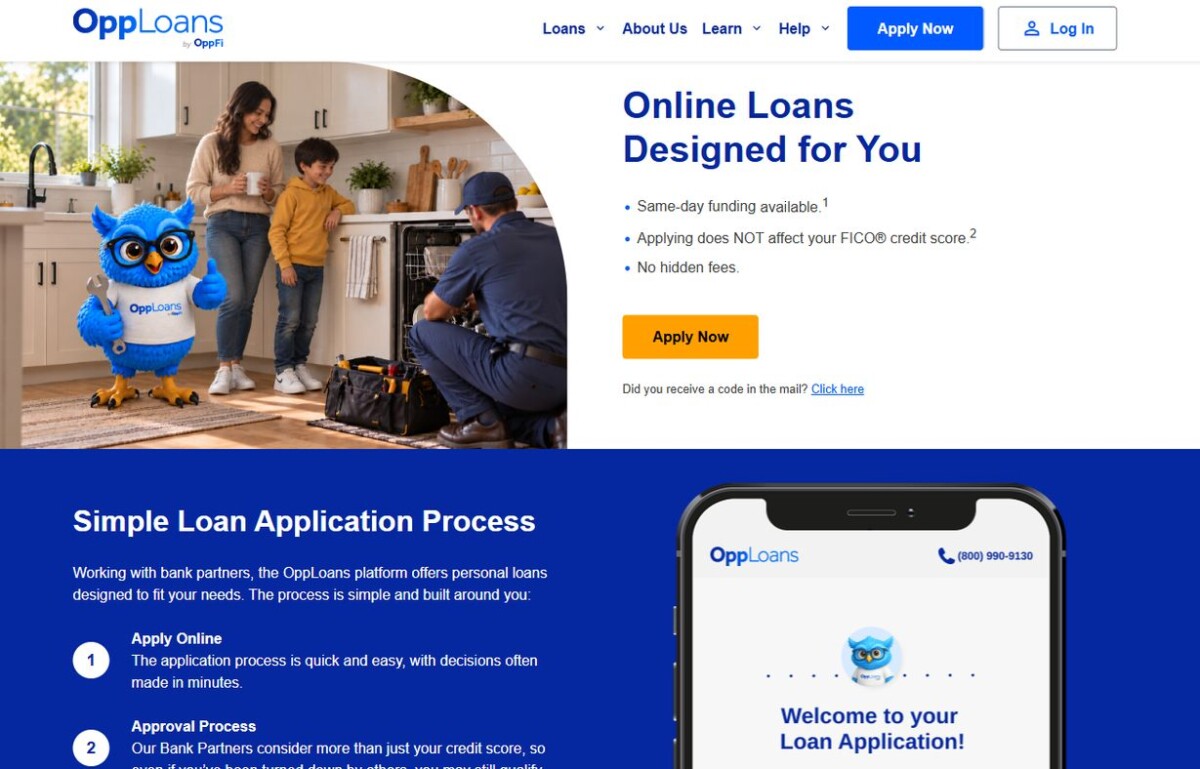
OppLoans works well for those who need to move fast without worrying about their credit score. Their platform is built for people who might have been turned down by traditional banks due to a less-than-perfect history. They prioritize accessibility for people who are often overlooked by the big banks. Instead of looking only at a FICO score, they often consider your ability to repay through consistent income and banking history.
The application process is designed to be quick, often yielding decisions within minutes. If you are approved, same-day funding can be a huge relief when an emergency strikes. It is a practical tool for those needing a bridge to the next paycheck, acting as a buffer between a sudden expense and your next direct deposit.
Pros:
- Applying does not affect your FICO credit score.
- Same-day funding is available for approved applicants.
- No hidden fees in the fine print.
Cons:
- Loan amounts are limited compared to larger banks.
2. MaxCash
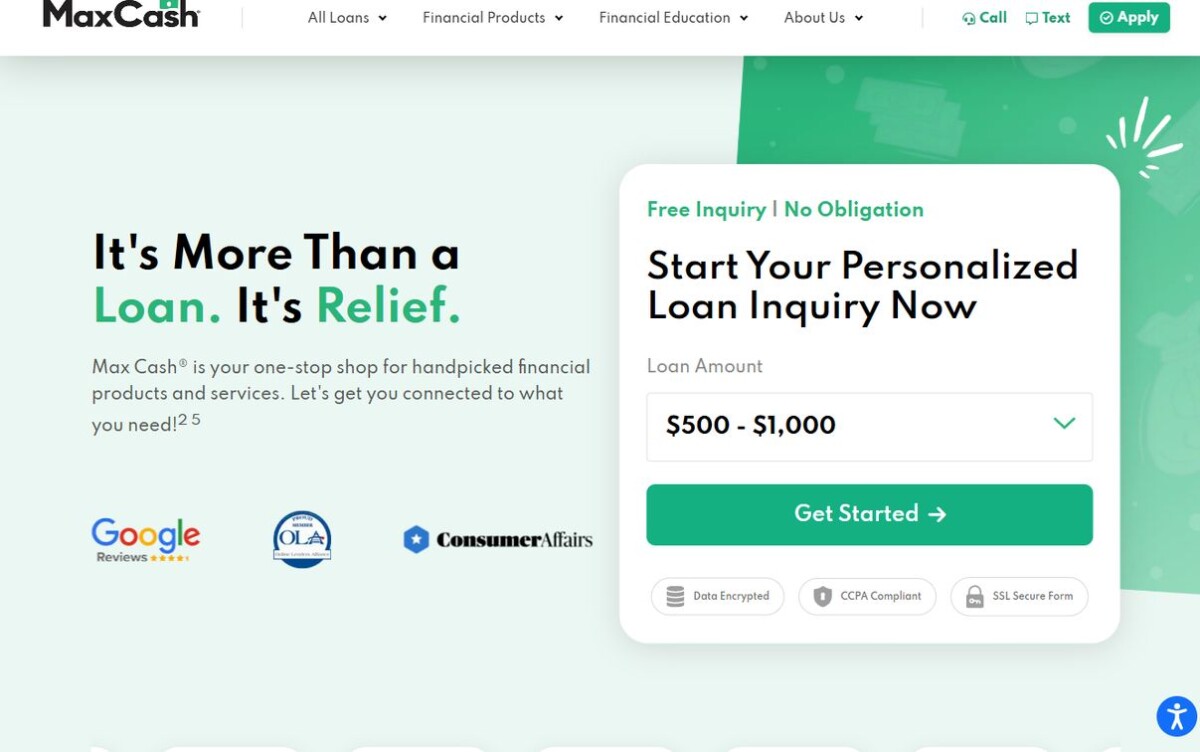
MaxCash functions as a versatile shop for various financial needs, ranging from simple cash advances to significant installment loans. They offer a wide spectrum of loan amounts, making them a flexible choice for different levels of urgency. If you need $300 to cover a utility bill, they can help. If you need $5,000 to repair a vehicle used for work, they can accommodate that too.
The platform is highly accessible, allowing for a personalized inquiry without any obligation. Whether you need a small amount for groceries or a larger sum for a car, their diverse product list covers many bases for Virginia residents. The ability to check your eligibility without a hard inquiry is a standout feature for anyone testing different lending products.
Pros:
- Wide range of loan amounts from $250 to $10,000+.
- Free inquiry with no obligation to move forward.
- Offers various products including title and installment loans.
Cons:
- The variety of products can be overwhelming for some users.
3. JetzLoan
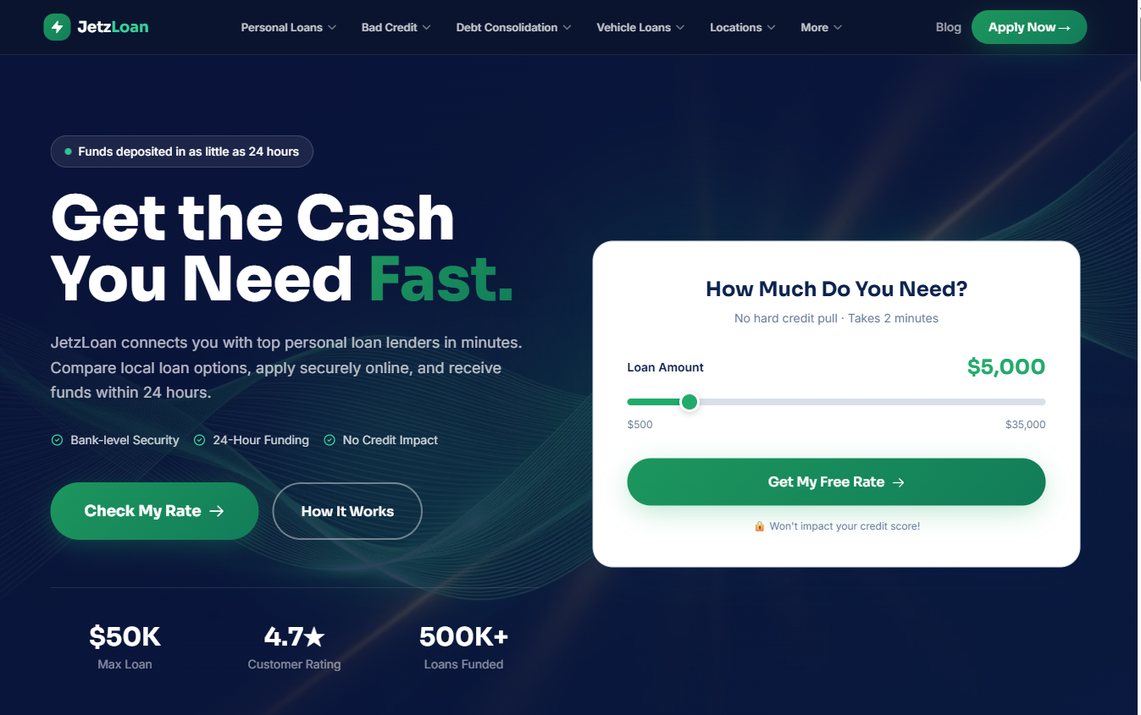
JetzLoan focuses heavily on transaction speed, aiming to get funds into your account in as little as 24 hours. This is ideal for someone who needs a quick fix for a sudden problem and doesn’t want to wait a week for processing. Their digital-first approach minimizes the red tape that often plagues traditional lending. (jetzloan.com)
They offer significant loan amounts, reaching up to $35,000, which is quite substantial for a lender that emphasizes speed. This makes them a viable option for larger, unexpected expenses like a major medical procedure or an urgent home repair. Their process is transparent, and the “no hard credit pull” feature ensures your score remains untouched during the initial phase.
Pros:
- High customer rating of 4.7 stars.
- Fast funding within 24 hours of approval.
- No hard credit pull during the rate check.
Cons:
- The quick application may feel rushed to some users.
4. Vacu
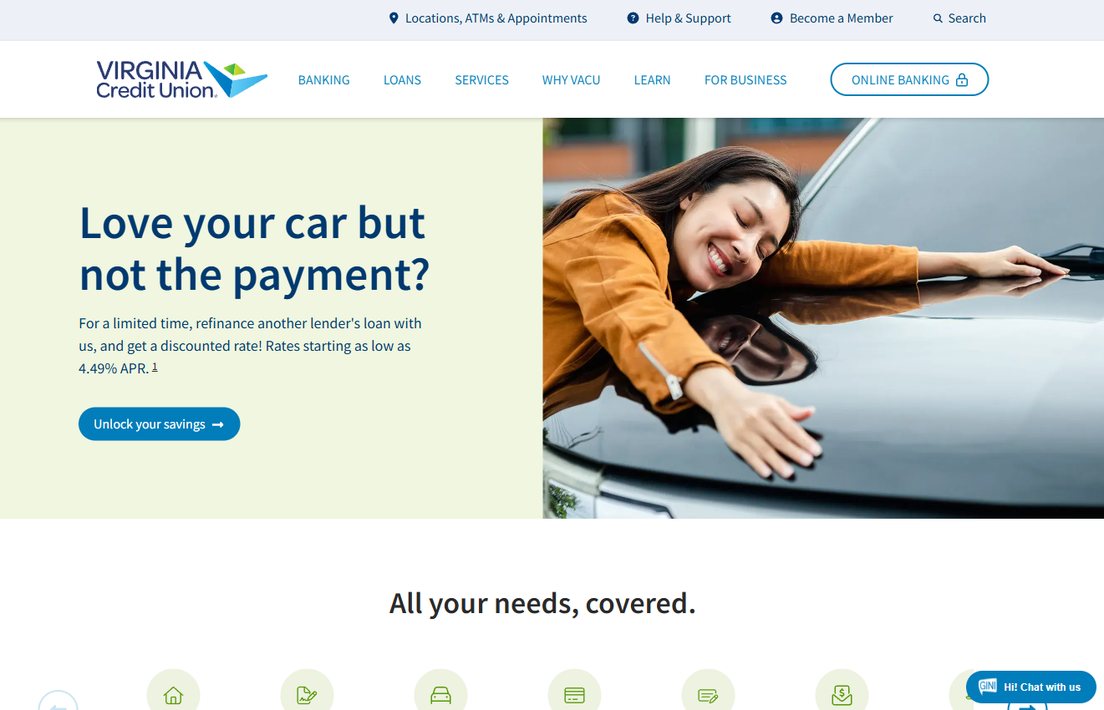
Vacu operates more like a traditional credit union, which often means a different level of service. Unlike many online-only lenders, credit unions are member-owned. This can sometimes translate to more favorable terms for those who qualify. They offer personal loan options that can be as low as $100, providing a safety net for small needs like a quick trip to the pharmacy.
One interesting feature is their ability to help you refinance other loans, sometimes offering rates as low as 4.49% APR for specific refinancing scenarios. This can be a powerful tool for anyone looking to consolidate debt and lower monthly payments. By rolling several high-interest debts into a single, lower-interest loan, you can streamline your budget and free up monthly cash flow.
Pros:
- Very low entry point for loan amounts.
- Potential for refinancing existing loans at lower rates.
- Offers a wide array of banking services beyond loans.
Cons:
- Credit union membership requirements may apply.
5. 1st Advantage
1st Advantage is a specialized option for those facing very immediate, short-term needs. Their short-term loans can go up to $750 and are specifically geared toward people who need to bridge a gap quickly without a standard credit check. This is a high-speed, low-complexity product designed for micro-emergencies.
This is a niche product meant for small, urgent expenses. It is not the place to go if you are looking to buy a car or renovate a kitchen, but for a quick emergency fix—like an unexpected $200 car maintenance fee—it is a very direct route. The simplicity of the application means you spend less time on a keyboard and more time solving the actual problem.
Pros:
- No credit check required for certain short-term loans.
- Specifically designed for urgent, unexpected expenses.
- Simple application for quick cash needs.
Cons:
- Loan amounts are relatively low compared to other lenders.
Understanding the Cost of Borrowing: APR vs. Monthly Payment
When you are in a rush, the most tempting number is the monthly payment. If a lender tells you that you only have to pay $50 a month, it sounds much more manageable than a lump sum. However, this is often where the hidden math of lending lives. You must look closely at the Annual Percentage Rate (APR). The APR includes interest and any origination fees or processing costs.
Consider this comparison:
| Scenario | Monthly Payment | Total Interest/Fees Paid | Total Cost of Loan |
|---|---|---|---|
| Option A (Lower APR) | $100 | $200 | $1,200 |
| Option B (Higher APR) | $75 | $500 | $1,300 |
In the example above, Option B seems cheaper on a month-to-month basis, but it actually costs you more in the long run. Always calculate the total amount you will have paid by the end of the loan term. This “Total Cost of Credit” is the only number that truly reflects the impact on your long-term financial health.
How to Prepare for a Successful Application
To maximize your chances of approval and secure the best possible rates, you should gather your documentation before you even hit the “Apply” button. Most lenders will require a digital copy or a photo of the following:
- Proof of Identity: A valid driver’s license or state-issued ID.
- Proof of Income: Recent pay stubs, W-2 forms, or bank statements showing regular deposits.
- Proof of Residency: A utility bill or lease agreement that matches your application address.
- Active Bank Account: Most lenders will deposit funds via ACH, so ensure your routing and account numbers are handy.
Being organized doesn’t just speed up the process; it prevents errors. A single typo in your social security number or a mismatched address can trigger a manual review. This could delay your funding by several days, which is a critical delay if you are facing a time-sensitive emergency.
Navigating Your Borrowing Decisions
Choosing a lender is a bit like picking a pair of shoes; it has to fit your specific situation perfectly. If you need a large sum for a long-term project, a credit union might be your best bet. However, if your car broke down this morning, speed becomes your most important metric. There is no one-size-fits-all in the lending world; there is only the option that best serves your current crisis and your future budget.
Avoid the trap of only looking at the monthly payment amount. It is easy to get distracted by a small number, but the total cost of borrowing—including interest and any fees—is what actually impacts your wallet in the long run. Always read the terms to ensure there are no surprises, such as prepayment penalties that charge you a fee if you try to pay the loan off early.
Another common mistake is applying for multiple loans at once from different lenders. Even if the lender uses a soft pull that doesn’t hurt your score, a sudden spike in applications can sometimes raise red flags with traditional creditors later on. They may view multiple recent inquiries as a sign of credit seeking, which can suggest you are in deeper financial trouble than you actually are. Take a moment to breathe and compare your options carefully.
