Uncategorized
The 5 Best Lenders for Bad Credit Loans in Maryland for 2026
The 5 Best Lenders for Bad Credit Loans in Maryland for 2026
Last updated: 2026-10-17
Navigating the financial landscape in Maryland can feel like trying to walk through a thick fog without a flashlight. When a sudden car repair, an unexpected medical bill, or a home maintenance emergency lands on your doorstep, the pressure mounts instantly. Many residents find themselves searching for a lifeline when their credit score doesn’t reflect their true reliability or character—perhaps due to a past period of unemployment, a medical crisis, or simply the rising costs of living in the Baltimore-Washington corridor.
Finding the right lender requires more than just a quick search on a mobile device. It involves weighing speed against cost, understanding the difference between secured and unsecured debt, and identifying which institutions prioritize your actual situation over a mere three-digit number. Whether you are navigating the suburbs of Montgomery County or the urban centers like Baltimore, understanding the nuances of the lending market is essential to maintaining financial stability.
This list highlights options specifically suited for those facing hurdles in the Old Line State, providing a starting point for anyone needing to bridge a temporary gap in their budget.
- FastLendGo
- MaxCash
- LendingPoint
- OppLoans
- SECU
How Maryland Lenders Were Evaluated
Selecting these providers involved a deep dive into their specific offerings for Maryland residents. The focus remained on accessibility for those with subprime or poor credit scores, ensuring that the lenders listed were not just available, but actually useful to those in a high-stress financial position. It is not just about getting cash; it is about finding a path that does not lead to a deeper debt trap through predatory interest rates or hidden fees.
Each entry was scrutinized based on several critical metrics:
- Stated Loan Amounts: We looked for a range that accommodates both small, immediate needs (like a $300 utility bill) and larger structural needs (like $15,000 for debt consolidation).
- Speed of Funding: In an emergency, time is of the essence. We evaluated whether a lender provides instant decisions, same-day funding, or a multi-day waiting period.
- Transparency and Requirements: We looked for clarity in their processes to ensure that what you see on the screen matches the reality of the loan agreement when it comes time to sign.
- Credit Impact: We prioritized lenders that offer “soft pull” inquiries for initial quotes, allowing you to shop around without further damaging your FICO score.
| Lender Name | Loan Amounts | Funding Speed | Credit Requirements |
|---|---|---|---|
| FastLendGo | $500 – $5,000+ | Fast access | Bad/Fair/Good Credit |
| MaxCash | $250 – $10,000+ | Minutes | Bad Credit Loans |
| LendingPoint | $1,000 – $36,500 | Fast decision | See site |
| OppLoans | See site | Same-day funding available | Does not affect FICO score |
| SECU | $300 – $30,000 | See site | Unsecured Signature Loans |
Understanding Loan Types: Secured vs. Unsecured
Before choosing a lender from the list below, it is vital to understand the mechanism of the loan you are requesting. In Maryland, lenders typically offer two primary structures: secured and unsecured loans. This distinction can be the difference between a manageable debt and a significant loss of assets.
Unsecured Loans
An unsecured loan is not backed by any collateral. When you take out an unsecured personal loan—such as many of the options offered by LendingPoint or SECU—the lender is relying solely on your promise to pay them back. Because there is no asset for the lender to seize if you default, these loans often require a more thorough review of your income and banking history. If you have a steady paycheck but a low credit score, an unsecured loan is often the safest way to borrow without risking your property.
Secured Loans
A secured loan is backed by an asset, often referred to as collateral. For example, if you use a title loan (a product mentioned in the MaxCash section), your vehicle serves as the guarantee for the debt. If you are unable to repay the loan, the lender has the legal right to seize the vehicle to recoup their losses. While secured loans are often easier to obtain for those with very poor credit because the lender’s risk is lower, they carry a much higher personal risk if your financial circumstances do not improve.
Top Maryland Lenders for Challenging Credit
1. FastLendGo
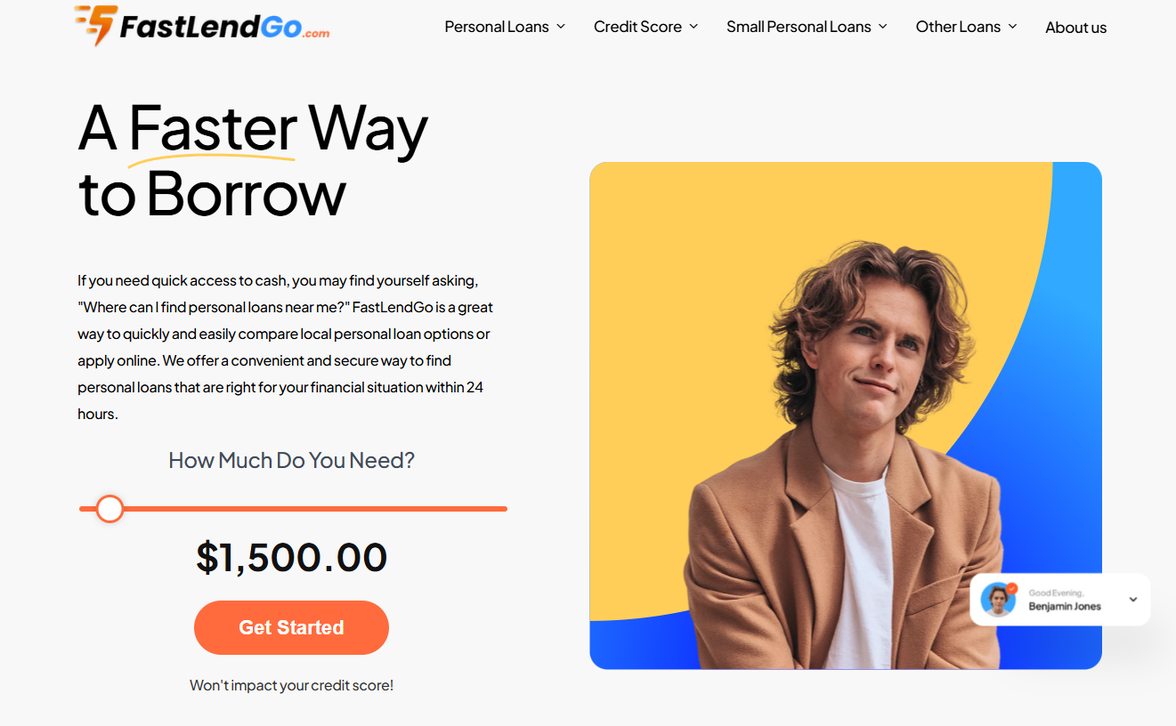
FastLendGo acts as a bridge for those who need a quick way to compare various local personal loan options. It is designed for people who need to move fast, whether that means covering an emergency auto repair or handling a sudden dental expense that cannot wait for the next pay cycle. The platform focuses on speed and simplicity for the borrower, reducing the bureaucratic friction often found in large national banks. (fastlendgo.com)
This provider is particularly useful for those who need specific amounts, ranging from small $500 injections to larger $5,000 personal loans. They cater to a wide spectrum of credit profiles, making them a versatile choice for Marylanders in a pinch. Because they act as a conduit to various options, they can often find a match that a traditional bank might overlook.
Pros:
- Offers various loan purposes including auto and dental.
- Covers a wide range of credit levels from bad to great.
- Quick access to compare local options.
Cons:
- Does not specify exact interest rates in the overview.
2. MaxCash
MaxCash positions itself as more than just a lender; it aims to be a source of relief. For residents in Maryland dealing with urgent needs, such as a utility shut-off notice or an immediate repair, this service provides a way to access installment or title loans in a matter of minutes. It is built for speed and immediate financial relief, making it a high-velocity option for urgent cash flow gaps.
The flexibility in loan amounts is a standout feature, starting as low as $250 and scaling up to over $10,000. This makes it a “one-stop shop” for various financial products. If you need a quick cash advance to bridge the gap until payday, this is a primary contender for those who need liquidity instantly rather than waiting for a multi-day bank transfer.
Pros:
- Extremely fast processing, sometimes in minutes.
- High maximum loan amounts for title loans.
- Multiple loan types available.
Cons:
- Title loans involve using your vehicle as collateral.
3. LendingPoint
LendingPoint focuses on unlocking possibilities for people who need more significant capital. With loan amounts reaching up to $36,500, this is a robust option for those looking at debt consolidation or major home improvements. If you have several high-interest credit card balances that are draining your monthly income, a single larger loan from a provider like this can be a strategic tool for long-term financial restructuring.
The process is designed to be easy, allowing users to check their rates without impacting their credit score. This “soft pull” approach is a lifesaver for those trying to shop around without making their credit situation look even worse. It is ideal for those with specific, larger financial goals who need a professional, streamlined digital experience.
Pros:
- High loan ceiling for significant expenses.
- Checking rates does not affect credit score.
- Wide variety of loan purposes.
Cons:
- May require a higher credit tier than specialized bad credit lenders.
4. OppLoans
OppLoans is built around the idea that your credit score doesn’t tell the whole story. By working with bank partners, they offer personal loans designed to fit unique needs, even if you have been turned down elsewhere due to a recent dip in your score. It is a supportive option for those who feel overlooked by traditional banks that rely heavily on automated, rigid scoring models.
One of the most significant advantages here is the potential for same-day funding. If you are facing an immediate crisis—such as a broken furnace in the middle of a Maryland winter—the ability to get money in your account the same business day is a game-changer. The application process is streamlined to be quick and easy, requiring minimal documentation to get started.
Pros:
- Same-day funding available for approved applicants.
- Does not affect FICO score during application.
- No hidden fees in the advertised process.
Cons:
- Approval is based on more than just credit, which can be unpredictable.
5. SECU
SECU stands as Maryland’s largest state-chartered credit union, offering a more traditional, community-focused banking experience. Their unsecured signature loans are a solid choice for those who want to build a long-term relationship with a financial institution. As a member-owned entity, SECU often provides a level of service and community alignment that national banks simply cannot match.
They offer loans ranging from $300 up to $30,000 with no application or prepayment penalties. This flexibility is vital; if you receive a tax refund or a work bonus, you can pay off your SECU loan early without being punished with extra interest—a common tactic used by other lenders. It is a refreshing change for those used to the predatory terms and “early repayment penalties” of some high-interest lenders.
Pros:
- No application or prepayment penalties.
- High maximum loan amounts for an unsecured product.
- Strong community presence in Maryland.
Cons:
- Credit union membership requirements may apply.
Navigating Your Borrowing Choices
Choosing a lender is not a decision to be made in a vacuum. Before signing any paperwork, you must look closely at the fine print. It is easy to get caught up in the excitement of a quick approval, but the cost of that speed can be steep if you do not perform the necessary due diligence.
Avoid the mistake of only looking at the monthly payment. A low monthly payment often means a much longer term, which results in you paying significantly more interest over the life of the loan. For example, a $2,000 loan with a $100 monthly payment over 36 months is far more expensive than a $2,000 loan with a $200 monthly payment over 12 months. Always calculate the total cost of the loan—the sum of all your payments—before you commit your signature.
Another common pitfall is failing to compare the lender’s reputation with your specific needs. If you need money today to prevent an eviction, a credit union might be too slow, even if they have better rates. Conversely, if you need $20,000 to consolidate your debts and lower your interest burden, a small cash advance lender won’t be able to help you reach that goal and may actually make your situation worse.
Lastly, remember that “guaranteed approval” is a myth in the lending world. Legitimate lenders must assess your ability to repay to comply with consumer protection laws. Anyone claiming they cannot say no is likely a red flag for a scam or a predatory lender. Stick to reputable providers that clearly outline their criteria and respect your financial well-being as you navigate through difficult times.
